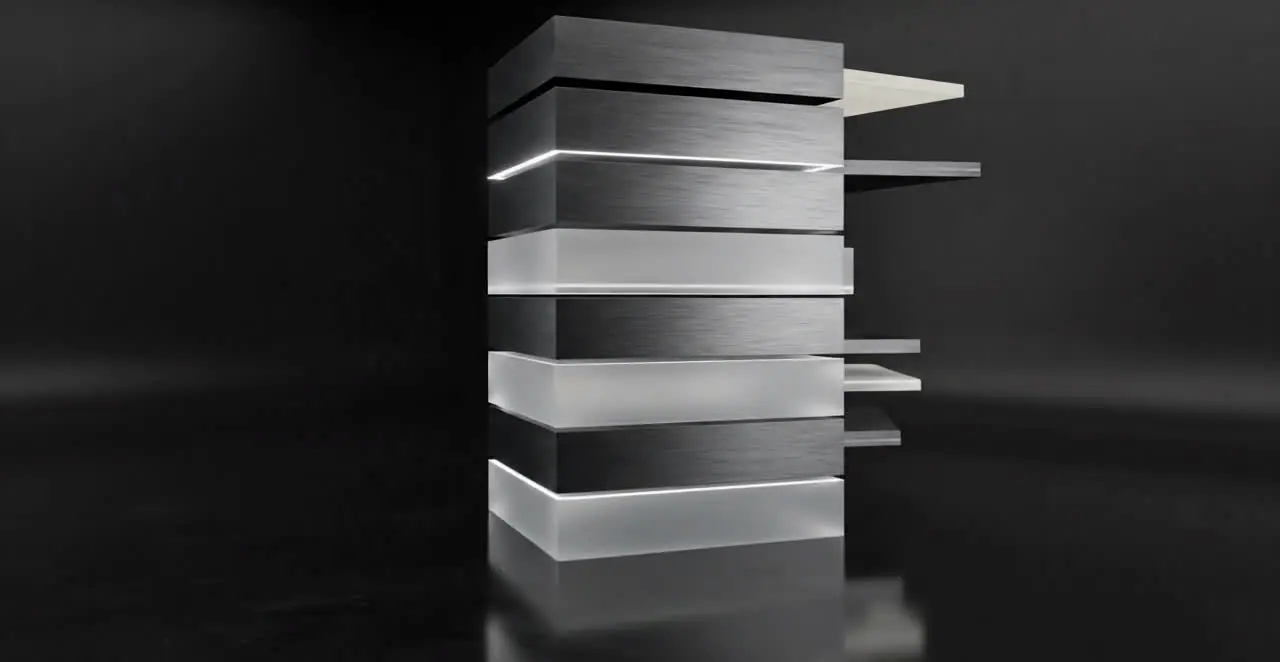
Every project is financed by a stack of capital. Each layer carries a different level of risk, expects a different return and has a different claim on cash flow. Getting the mix right is often the difference between a project that works and one that never starts.
The four layers
- Senior debt. The cheapest and safest layer, paid first. Usually from banks or development lenders, secured on the assets.
- Mezzanine. Sits between debt and equity. More expensive, but it reduces the equity a sponsor must contribute.
- Preferred equity. Ranks ahead of common equity, often with a fixed preferred return and limited upside.
- Common equity. The first to absorb losses and the last to be paid — and the layer that captures the upside.
How we decide the mix
We start with the cash flows, not the capital. How predictable are they? Are they contracted, indexed or exposed to the market? The more certain the cash flow, the more senior debt a project can carry safely.
Then we ask what the sponsor needs: control, speed, a lower cost of capital or more flexibility. A project with strong contracted revenue might carry seventy percent debt; an early-stage development might need mostly equity.
The best capital stack is not the cheapest one. It is the one that survives a bad year.
Common mistakes
- Maximising leverage instead of resilience.
- Mismatching tenors — short debt for long assets.
- Ignoring currency risk between revenue and financing.
- Bringing in partners whose time horizon is shorter than the project’s.
Where we fit
We invest in mezzanine, preferred and common equity, and we arrange senior debt with lenders we know. Because we sit in several layers at once, our incentives are aligned with the project’s long-term health — not with any single tranche.